Interest Rate Forecasts 2026: Navigating a Potential 50 Basis Point Hike
As we cast our gaze towards the economic horizon of 2026, one of the most critical factors influencing global financial stability and individual prosperity is the trajectory of interest rate forecasts. The whispers of a potential 50 basis point hike loom large, sparking widespread discussions among economists, policymakers, businesses, and consumers alike. Understanding the nuances of such a significant monetary policy adjustment is paramount, as its ripple effects can touch every facet of the economy, from housing markets and investment portfolios to consumer spending and corporate profitability.
This comprehensive analysis delves into the intricate world of interest rate forecasts for 2026, exploring the multifaceted implications of a potential 50 basis point increase. We will dissect the driving forces behind these predictions, examine the historical context of similar hikes, and project the likely consequences across various economic sectors. By the end of this article, you will have a clearer understanding of what a higher interest rate environment could mean for your finances and the broader global economy.
Anúncios
Understanding the Basics: What are Interest Rates and Why Do They Matter?
Before diving into the specifics of 2026 interest rate forecasts, it’s crucial to establish a foundational understanding of what interest rates are and why they wield such immense power. In essence, an interest rate is the cost of borrowing money or the return on saving money. Central banks, like the Federal Reserve in the United States or the European Central Bank, use interest rates as a primary tool to manage monetary policy, influencing inflation, employment, and economic growth.
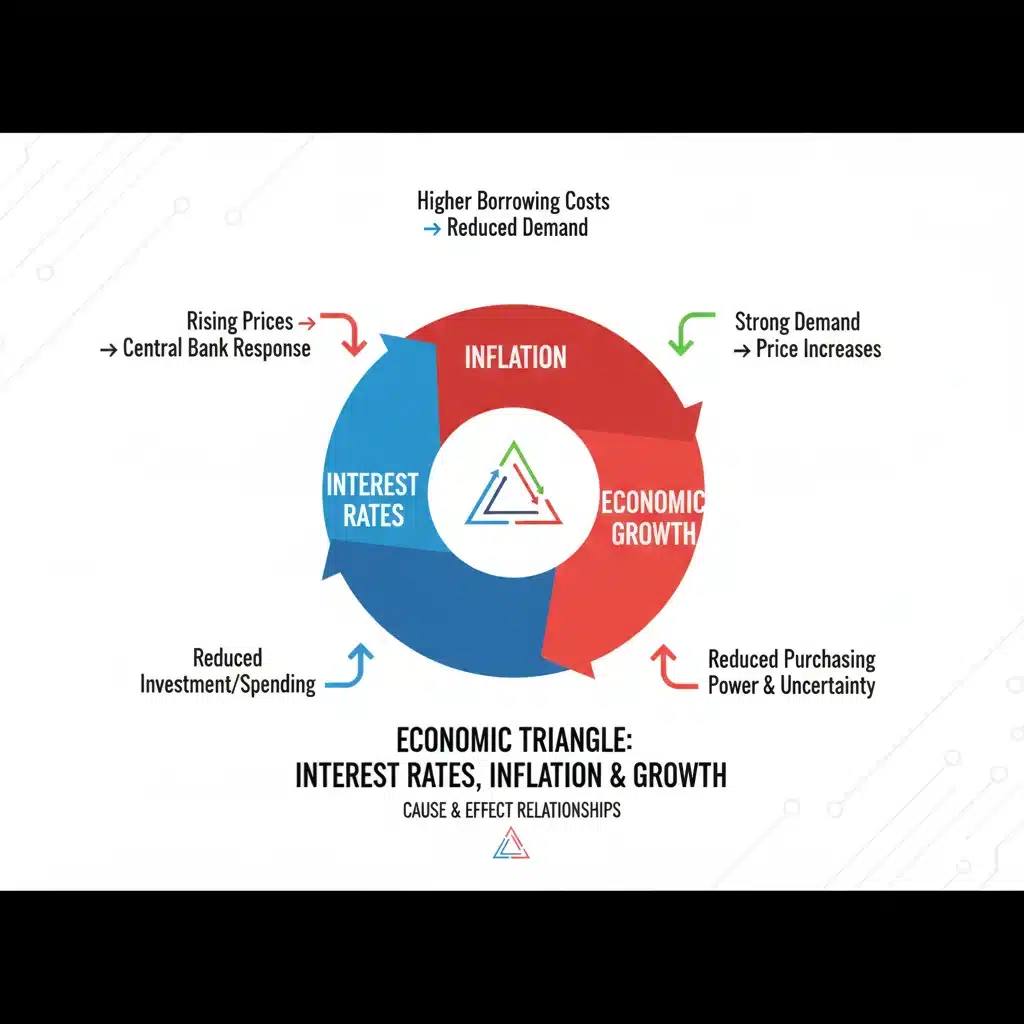
When central banks raise interest rates, they make borrowing more expensive. This discourages spending and investment, aiming to cool down an overheating economy and curb inflation. Conversely, lowering rates makes borrowing cheaper, stimulating economic activity during downturns. A 50 basis point hike, which translates to a 0.50% increase, is a substantial move, signaling a strong intent from policymakers to address specific economic challenges, typically persistent inflation.
Anúncios
The significance of interest rates extends far beyond mere borrowing costs. They impact:
- Consumer Spending: Higher rates mean more expensive loans for cars, homes, and credit card balances, potentially reducing discretionary spending.
- Business Investment: Companies face higher costs for capital, which can slow down expansion plans and job creation.
- Housing Market: Mortgage rates directly correlate with central bank rates, affecting affordability and demand.
- Savings and Investments: Savers may see better returns, while bond yields adjust, impacting equity markets.
- Exchange Rates: Higher rates can attract foreign capital, strengthening a country’s currency.
Therefore, any significant shift in interest rate forecasts, especially a potential 50 basis point hike, warrants close attention due to its far-reaching implications.
The Drivers Behind 2026 Interest Rate Forecasts: Inflation and Economic Growth
The primary catalysts for any central bank’s decision to adjust interest rates are inflation and economic growth. For 2026, the discussion around a 50 basis point hike is predominantly fueled by concerns over sustained inflationary pressures and the broader health of the global economy.
Persistent Inflacionary Pressures
The post-pandemic era has been characterized by elevated inflation rates across many major economies. Supply chain disruptions, robust consumer demand, geopolitical tensions, and energy price volatility have all contributed to a sustained period of rising prices. While some economists anticipate a gradual moderation, others fear that inflation could become entrenched, necessitating more aggressive monetary tightening.
Central banks have a dual mandate: to maintain price stability (control inflation) and foster maximum sustainable employment. When inflation consistently exceeds their target, they are compelled to act. A 50 basis point hike in 2026 would signal that central banks believe underlying inflationary forces remain strong, requiring a more forceful intervention to bring prices back under control.
Economic Growth and Labor Markets
The state of economic growth and labor markets also plays a crucial role in shaping interest rate forecasts. A robust economy with low unemployment typically gives central banks more leeway to raise rates without fear of triggering a recession. If growth remains strong through 2025 and into 2026, central banks might feel confident in implementing a significant rate hike to prevent the economy from overheating.
Conversely, a weakening economic outlook or signs of a recession could temper the enthusiasm for aggressive rate hikes. Policymakers must carefully balance the need to combat inflation with the risk of stifling economic activity. The 2026 forecast for a 50 basis point hike suggests that, for now, the perceived threat of inflation outweighs the immediate risks to economic growth, or that the economy is expected to be resilient enough to absorb such a shock.
Historical Context: Lessons from Past Rate Hikes
Understanding the potential impact of a 50 basis point hike requires looking back at historical instances of similar monetary tightening cycles. While every economic period is unique, past experiences offer valuable insights into common patterns and consequences.
Historically, aggressive rate hikes have often been employed to combat runaway inflation. For example, during the late 1970s and early 1980s, the Federal Reserve, under Chairman Paul Volcker, dramatically raised interest rates to quell double-digit inflation. While successful in bringing inflation down, these actions also led to significant economic slowdowns and recessions.
More recently, smaller, more gradual rate hike cycles have been observed, with central banks preferring a ‘wait and see’ approach. A 50 basis point hike is less common as a single-step move compared to 25 basis points, indicating a more urgent response to economic conditions. Such a move often signifies that previous, smaller adjustments have not had the desired effect, or that the economic situation has deteriorated rapidly.
Key takeaways from historical rate hikes include:
- Lagged Effects: Monetary policy decisions often have a delayed impact on the economy, typically taking 6-18 months to fully materialize.
- Sectoral Disparities: Some sectors, like housing and manufacturing, are more sensitive to interest rate changes than others.
- Market Volatility: Financial markets often react sharply to significant rate hikes, leading to increased volatility in stocks, bonds, and currencies.
Therefore, as we consider 2026 interest rate forecasts, historical precedents suggest that a 50 basis point hike would be a powerful tool with significant, albeit potentially delayed, consequences.
Impact on Key Economic Sectors
A 50 basis point hike in 2026 would send ripples across various economic sectors. Let’s explore some of the most affected areas.
The Housing Market: Affordability and Demand
The housing market is arguably one of the most sensitive sectors to changes in interest rates. Mortgage rates are directly tied to broader interest rate movements. A 50 basis point hike would translate to higher borrowing costs for prospective homeowners, significantly impacting affordability.
Potential consequences for the housing market include:
- Reduced Demand: Higher mortgage payments could price out some buyers, leading to a decrease in overall demand.
- Cooling Home Prices: With reduced demand and increased borrowing costs, the rapid appreciation of home prices seen in recent years could slow down or even reverse in some markets.
- Increased Inventory: Fewer buyers could lead to an increase in available homes, shifting the market dynamics from a seller’s to a buyer’s market.
- Refinancing Activity: Existing homeowners with adjustable-rate mortgages could see their payments increase, while fixed-rate mortgage holders would be less affected. Refinancing activity would likely decline.
For those planning to buy a home in 2026, keeping a close eye on interest rate forecasts and understanding the potential for higher mortgage costs will be crucial.
Investment Strategies: Stocks, Bonds, and Alternative Assets
Investors will need to recalibrate their strategies in response to a higher interest rate environment. The relationship between interest rates and various asset classes is complex and often inverse.
Stocks
Higher interest rates typically make borrowing more expensive for companies, which can reduce corporate profits and slow down expansion plans. This can lead to downward pressure on stock valuations, especially for growth stocks that rely heavily on future earnings. Value stocks, which are often less sensitive to interest rate changes, might fare relatively better. Sectors like technology and other high-growth industries could experience headwinds, while more stable, dividend-paying sectors might attract more attention.
Bonds
Bond prices generally move inversely to interest rates. When interest rates rise, newly issued bonds offer higher yields, making existing bonds with lower yields less attractive, thus driving their prices down. However, for investors looking to lock in higher returns, a 50 basis point hike presents an opportunity to invest in new bonds with more attractive yields. Short-term bonds tend to be less sensitive to rate changes than long-term bonds.
Alternative Assets
Alternative assets such as real estate (beyond residential), commodities, and private equity will also feel the impact. Real estate investment trusts (REITs) might face challenges due to higher borrowing costs and potentially slower property value appreciation. Commodities, while often seen as an inflation hedge, can also be affected by a stronger dollar, which typically accompanies higher rates. Investors will need to diversify and carefully assess risk in this environment.
Businesses and Corporate Finance
For businesses, a 50 basis point hike means higher costs of capital. This impacts everything from operating loans to financing new projects and mergers and acquisitions. Companies with significant variable-rate debt will see their interest expenses increase, potentially squeezing profit margins. Businesses will likely become more cautious with their spending and investment plans, prioritizing efficiency and debt reduction.
Small and medium-sized enterprises (SMEs), which often have less access to diverse funding sources than large corporations, could feel the pinch more acutely. Access to affordable credit is vital for their growth and survival. Therefore, the 2026 interest rate forecasts will be a critical factor in strategic planning for businesses of all sizes.
Consumers and Personal Finance
Consumers will experience the effects of higher rates through several channels:
- Credit Card Debt: Most credit cards have variable interest rates, so outstanding balances will become more expensive to carry.
- Auto Loans: New car loans and used car loans will likely see higher interest rates, increasing monthly payments.
- Student Loans: For those with variable-rate student loans, payments could rise.
- Savings Accounts: On the positive side, savers might see slightly higher returns on their savings accounts, money market accounts, and Certificates of Deposit (CDs).
The overall impact on consumer spending could be a slowdown, as households prioritize debt repayment and face higher costs for essential goods and services due to persistent inflation. This combination could lead to a more conservative consumer behavior pattern.
Global Economic Implications
Interest rate decisions by major central banks, particularly the U.S. Federal Reserve, have significant global repercussions. A 50 basis point hike in the U.S., for instance, could lead to a stronger U.S. dollar. This has several implications:
- Emerging Markets: Countries with dollar-denominated debt would face higher repayment costs, potentially leading to financial instability. A stronger dollar can also make imports more expensive for these nations.
- Trade: A stronger dollar makes U.S. exports more expensive and imports cheaper, impacting trade balances.
- Capital Flows: Higher U.S. rates can attract capital away from other countries, potentially putting pressure on their currencies and financial markets, possibly forcing their central banks to also raise rates to stem capital outflows.
Therefore, the 2026 interest rate forecasts are not just a domestic concern but a global economic event that requires coordinated assessment and response from international policymakers.
Challenges and Uncertainties in Forecasting
While economists use sophisticated models and data to generate interest rate forecasts, the future is inherently uncertain. Several factors could alter the trajectory of rates in 2026:
- Geopolitical Events: Unforeseen conflicts, trade wars, or political instability can disrupt supply chains, impact energy prices, and alter economic growth, forcing central banks to revise their plans.
- New Economic Data: Inflation data, employment reports, and GDP figures can surprise analysts, leading to shifts in central bank sentiment.
- Technological Advancements: Breakthroughs in technology could boost productivity and potentially ease inflationary pressures, or conversely, create new demand-side pressures.
- Fiscal Policy: Government spending and taxation policies can either complement or contradict monetary policy, influencing its effectiveness.
- Consumer and Business Sentiment: Changes in confidence levels can significantly impact spending and investment, creating a self-fulfilling prophecy of economic expansion or contraction.
Therefore, while a 50 basis point hike is a plausible scenario for 2026, it’s crucial to remain adaptable and monitor economic developments closely. The interest rate forecasts are dynamic and subject to continuous revision.
Strategies for Individuals and Businesses to Prepare
Given the potential for a 50 basis point hike in 2026, proactive planning is essential for both individuals and businesses.
For Individuals:
- Review Debt: Prioritize paying down high-interest variable debt, such as credit card balances. Consider refinancing fixed-rate debt if current rates are significantly lower than future projections, though this is less likely in a rising rate environment.
- Boost Savings: Higher rates mean better returns on savings. Maximize contributions to high-yield savings accounts or Certificates of Deposit.
- Investment Portfolio Review: Reassess your asset allocation. Consider diversifying into sectors that historically perform well during rising rate environments, or those less sensitive to interest rate fluctuations. Discuss with a financial advisor.
- Budgeting: Account for potentially higher costs for mortgages, auto loans, and other forms of credit in your personal budget.
For Businesses:
- Debt Management: Evaluate existing debt structures. Consider hedging strategies to mitigate interest rate risk on variable-rate loans. Secure financing for planned investments sooner rather than later if rates are expected to rise.
- Cost Control: Focus on operational efficiencies and cost management to maintain profit margins in a higher-cost environment.
- Pricing Strategy: Carefully assess pricing strategies to balance maintaining competitiveness with covering increased borrowing costs and input prices.
- Cash Flow Management: Optimize cash flow to reduce reliance on external borrowing.
- Scenario Planning: Develop different financial scenarios based on various interest rate forecasts to prepare for different outcomes.
The Role of Central Banks and Communication
Central banks play a pivotal role in shaping economic expectations through their communication. Forward guidance, speeches, and minutes from policy meetings are closely scrutinized by markets. The way central banks communicate their intentions regarding future interest rate forecasts can have a significant impact, even before any actual rate changes occur.
Should a 50 basis point hike be on the table for 2026, central banks would likely engage in clear and consistent communication to prepare markets and the public. This transparency aims to prevent undue volatility and allow economic actors to adjust their plans accordingly. However, striking the right balance between signaling intent and avoiding panic is a delicate act.
The credibility of central banks is also crucial. If their actions align with their stated goals of controlling inflation and fostering stability, markets are more likely to trust their guidance, leading to smoother transitions during periods of monetary tightening.
Conclusion: Preparing for a Dynamic Economic Landscape
The prospect of a 50 basis point hike in 2026 underscores a dynamic and potentially challenging economic landscape. While such a move by central banks would primarily be aimed at taming persistent inflation and ensuring long-term economic stability, its short-to-medium-term effects would be felt across virtually all sectors.
From the affordability of housing and the profitability of businesses to the returns on investment portfolios and the cost of consumer credit, interest rate forecasts for 2026 demand careful consideration. Individuals and businesses that proactively assess their financial positions, adapt their strategies, and stay informed about economic developments will be better positioned to navigate the potential headwinds and capitalize on any emerging opportunities.
Ultimately, while the precise timing and magnitude of future rate adjustments remain subject to evolving economic conditions, understanding the potential impact of a significant hike like 50 basis points is an indispensable step towards securing financial resilience in the years to come. The journey through 2026 will undoubtedly be influenced by these critical monetary policy decisions, making continuous monitoring and informed decision-making key to success.